The danger of home country bias and how to avoid it
TL;DR
Home country bias is the tendency to invest too heavily in companies and assets from your own country simply because they feel familiar. For British investors and expats, excessive exposure to the UK can reduce diversification and leave a portfolio unnecessarily dependent on one economy, currency and group of sectors. A globally diversified investment strategy spreads exposure across different countries, companies and industries, helping to reduce concentration risk, although diversification does not guarantee higher returns or protect against investment losses.
Is Your Portfolio More UK-Focused Than You Realise?
Home country bias is not always obvious. You may have a UK pension, investment funds, employer shares and other assets that each appear reasonably diversified when viewed individually, but together leave a much larger proportion of your wealth exposed to the UK than you realise.
For British expats, there is another dimension to consider. Where you live now, where you expect to retire, the currencies in which you are likely to spend your money and the countries in which your assets are held can all influence how your investment portfolio fits into your wider financial plan.
I can help you review your existing pensions and investments, understand where your underlying investment exposure actually lies and consider whether your portfolio remains aligned with your risk profile, retirement objectives and longer-term plans.
Updated: 17 September 2026
Home Country Bias
Home country bias occurs when investors concentrate their portfolios in shares and bonds from their home country.
For example, while the UK stock market now represents only around 3.1% of the value of global equity markets (compared with 10.4% in 2006), British investors tend to allocate considerably more than this to UK stocks.
Excessive home country bias can increase concentration risk by making an investment portfolio more dependent on the performance of a single market, economy and group of sectors.
What causes home country bias?
Whether consciously or not, investors tend to tilt their portfolios towards their home country. This typically happens due to one or more of a number of reasons:
Familiarity
We like to invest in things that we know.
“In investing, what is comfortable is rarely profitable.”
– Rob Arnott, founder and Chairman of Research Affiliates
Perception of risk
Due to factors such as corporate governance, investors perceive foreign investments as more risky than domestic ones.
Currency risk
Fluctuations in exchange rates can impact the return on foreign investments.
Personal experience
I have known clients invest in a company because a friend or family member works there.
They feel that this gives them an insight into the health of the company; we are less likely to have friends/family members working for a company in a country other than our own.
Employer Pensions and Share Ownership Plans
Your workplace pension and employee share schemes can contribute to home country bias, but it is important to look at what you actually own rather than assuming that a UK pension means your money is predominantly invested in the UK.
Many modern UK pension funds invest across global markets. However, older pension arrangements, particular investment funds or choices made within a pension may still leave you with more UK exposure than you realise.
Employer share schemes can create a different type of concentration risk. If you receive shares in the company you work for and continue accumulating them over many years, a significant proportion of your wealth can eventually become tied to a single business.
For British expats, the overall picture can become particularly difficult to see when UK pensions, personal investments, employer shares and investments accumulated overseas are held across several different accounts or countries.
The important question is therefore not simply where your pension or investment account is based, but where the underlying assets are actually invested and how those holdings contribute to your overall portfolio exposure.
Multinational companies
Some investors rely on investing in domestic companies with a global presence as a means of diversification.
However, while multinational domestic companies do provide exposure to global markets, it is not the same as investing directly into those markets.
While a multinational company may generate revenue around the world, owning shares in domestic multinationals is not necessarily equivalent to holding investments directly across multiple international markets.
Why does it matter?
Home country bias matters because excessive exposure to a single market can increase concentration risk within an investment portfolio. Individual country markets are generally less diversified than the global equity market, meaning investors can become disproportionately exposed to particular companies, sectors and economic conditions without necessarily realising it.
A single country’s stock market can also be heavily concentrated in particular companies and industries. A global equity portfolio, by contrast, can provide exposure to thousands of companies across numerous countries, sectors and economic environments.
This matters because different markets have very different characteristics. The UK market, for example, has historically had substantial exposure to sectors such as financials, energy and consumer staples, while the US market has a much greater weighting towards technology and communication services.
By concentrating heavily in your home market, you may therefore be making a much larger sector bet than you realise. Global diversification can reduce this dependence by spreading exposure across a broader range of businesses, industries and economies.
The power of diversification
Diversification is fundamentally about managing investment risk rather than predicting which market will perform best. Spreading investments across global markets can reduce reliance on the fortunes of any single country, sector or group of companies.
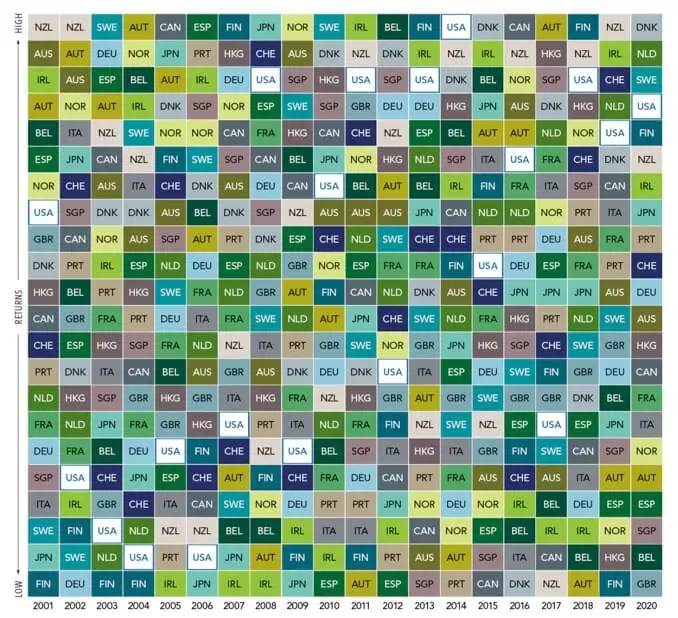
For example, in the chart below, the US ranked in the top five for annualised returns over the entire 20 years but finished first in the country rankings just once over that period. In nine calendar years, it was in the lower half of performers.
Meanwhile, in 2017, Austria posted the highest developed markets return but then followed that up with the lowest return the following year.
This illustrates why relying too heavily on any one country can create unnecessary concentration risk: market leadership can change significantly from one year to the next.
Equity returns of developed markets
Is Home Country Bias Affecting Your Investment Portfolio?
Identifying home country bias is not simply a matter of counting how many UK funds you own. Your true exposure may be spread across pensions, investment accounts, employer shares and funds holding companies from many different markets.
For British expats, the picture can be more complicated still. Geographic exposure, sector concentration, currency considerations and where you expect to live and spend your money in retirement can all influence whether your investments remain appropriate for your wider financial plans.
I can help you look across your pensions and investments as a whole, understand where your underlying exposure lies and identify areas where you may be more heavily concentrated in a particular country, company, sector or currency than you realise.
From there, we can consider how your investment strategy fits with your risk profile, retirement objectives, country of residence and longer-term plans rather than looking at individual investments in isolation.
How to Identify and Reduce Home Country Bias
Many investors do not realise how much exposure they have to their home country. Investments may be spread across pensions, ISAs, investment accounts, employer share schemes and other holdings, making the overall geographical allocation difficult to see.
The first step is therefore not necessarily to change your investments. It is to understand what you already own.
1. Look Through Your Funds to the Underlying Investments
A pension or investment account may contain several different funds, and the name of the account itself tells you very little about where your money is actually invested.
Review the underlying holdings and geographical allocations of each fund to establish how much exposure you have to the UK and other markets.
2. Look at Your Entire Portfolio
Home country bias should be assessed across your overall financial position rather than account by account.
You might have a globally diversified personal investment portfolio but still have significant UK exposure through an old workplace pension, employer shares or other investments accumulated over many years.
It is the combined exposure that matters.
3. Check for Company and Sector Concentration
Geographical diversification is only part of the picture. You should also consider whether a large proportion of your portfolio is concentrated in a particular company or industry.
This can be especially important if you hold shares in your employer. Your salary and career may already depend on that company, so holding a substantial proportion of your investments in the same business can increase your overall financial exposure to its fortunes.
4. Consider Currency Exposure Separately
Geographical diversification and currency exposure are not the same thing. A company listed in one country may earn revenues in many different currencies, while an internationally diversified portfolio can expose you to movements between sterling and other currencies.
For British expats, currency considerations can be particularly important because the currency in which you invest may be different from the currencies in which you earn income or expect to spend money during retirement.
5. Compare Your Portfolio With Your Actual Objectives
Once you understand your existing exposure, consider whether it makes sense in the context of your investment objectives, attitude to risk, retirement plans, country of residence and future spending needs.
For British expats, this should also take account of whether you intend to remain overseas, move to another country or eventually return to the UK.
6. Consider Whether Broader Global Diversification Is Appropriate
One way investors can reduce excessive home country bias is by increasing exposure to a broader range of global markets. Global or market-cap-weighted funds can provide access to companies across many countries and sectors within a single investment.
However, there is no single geographical allocation that is appropriate for everyone. The right approach will depend on your circumstances, objectives, risk profile and wider financial plan.
The objective is not necessarily to eliminate UK investments. It is to make sure the amount you hold in the UK is a deliberate investment decision rather than an unintended consequence of familiarity, convenience or investments accumulated over time.
Common Home Country Bias Mistakes
Home country bias is not always the result of a deliberate investment decision. It can develop gradually as pensions, investments and employer shares accumulate over many years. For British expats, moving between countries can make the overall picture even harder to recognise.
Here are some of the most common mistakes to look out for when reviewing your investment portfolio.
1. Assuming a UK Pension Means Your Money Is Invested in the UK
Where a pension is based and where its underlying assets are invested are two different things. A UK pension may contain funds investing across companies and markets around the world.
Looking only at the pension provider or wrapper can therefore give you a misleading impression of your geographical exposure. It is the underlying investments that need to be considered.
2. Looking at Each Investment Account Separately
A pension, ISA or investment account may appear reasonably diversified when considered on its own. However, several individually diversified accounts can still leave your overall portfolio heavily exposed to the same country, sectors or companies.
This is particularly relevant for British expats who may have UK pensions and investments alongside assets accumulated while living overseas. Your total portfolio exposure matters more than the allocation within any single account.
3. Assuming UK Multinationals Provide Complete Global Diversification
Many UK-listed companies operate internationally and generate substantial revenues outside the UK. This can provide exposure to overseas economies and currencies, but it is not the same as investing directly across a broad range of international markets.
A portfolio concentrated in UK-listed multinational companies can therefore still have significant country, company and sector concentration.
4. Allowing Employer Shares to Become Too Large a Part of Your Wealth
Employee share schemes can be valuable, but regularly receiving or purchasing shares in your employer can gradually create a substantial single-company holding.
This can result in both your employment income and a significant proportion of your investment wealth depending on the fortunes of the same company. Employer shares should therefore be considered as part of your overall portfolio rather than viewed in isolation.
5. Confusing Currency Exposure With Geographical Diversification
Investing internationally and diversifying your currency exposure are related concepts, but they are not the same thing. A company listed in one country may earn revenues in several currencies, while a globally diversified investment may expose you to movements between sterling and multiple overseas currencies.
For British expats, this distinction can be particularly important because the currencies in which you invest, receive income and eventually spend money in retirement may all be different.
6. Trying to Eliminate UK Investments Completely
Reducing home country bias does not necessarily mean removing UK investments from your portfolio. UK assets may still form an appropriate part of a diversified investment strategy depending on your circumstances, objectives and risk profile.
The aim is to understand how much UK exposure you have and why you have it. Your allocation should be a deliberate investment decision rather than simply the result of familiarity, convenience or investments accumulated over time.
Why Home Country Bias Matters for British Expats
Home country bias can be particularly easy to overlook when you are a British expat. You may have left the UK years ago while still retaining pensions, investments, employer shares or other assets accumulated before you moved abroad. Over time, you may also have acquired investments and assets in your new country of residence.
The result can be a portfolio shaped more by where you have lived and worked than by a deliberate investment strategy. Looking at each pension or investment account separately may not reveal the extent of this concentration. It is the combined exposure across your overall portfolio that matters.
Where Will You Eventually Spend Your Money?
For an expat, investment planning is not simply about deciding how much exposure to have to the UK. You also need to consider where you expect to live in retirement and the currencies in which you are likely to spend your money.
A British expat planning to remain overseas permanently may have very different future spending requirements from someone intending to return to the UK. Your circumstances may be different again if you expect to divide your retirement between countries or have financial commitments in more than one currency.
Geographical Diversification and Currency Exposure Are Not the Same Thing
It is also important not to confuse where a company is listed with the currencies and economies to which your investment is exposed. A UK-listed multinational may generate much of its revenue overseas, while an international investment can still expose you to movements between sterling and other currencies.
Currency exposure therefore needs to be considered alongside geographical and sector diversification rather than treating them as the same issue.
Your Nationality Should Not Determine Your Portfolio
Being British does not automatically mean that a large proportion of your investments should be held in UK companies. Equally, becoming resident in another country does not necessarily mean that your portfolio should become heavily concentrated in that country’s market.
The appropriate investment approach depends on your objectives, attitude to risk, existing assets, retirement plans, future spending needs and wider financial circumstances. For British expats, these considerations can span several countries and may change again if you eventually return to the UK.
The aim of global diversification is not to predict which country will produce the highest returns. It is to avoid making the success of your long-term investment and retirement plans unnecessarily dependent on the fortunes of any single country, market or sector.
Real People, Real Results
“In just one year Ross has helped me enormously, firstly and most importantly to better understand my financial position, rather than putting it off, to look at where I want to get to and start making some simple changes in order to achieve this. I would not hesitate in recommending Ross.”
— Paul Martingell
More TestimonialsConclusion
The case for global diversification is not that international markets will always outperform the UK. No investor can know in advance which country, region or sector will deliver the strongest returns over the next five, ten or twenty years.
That uncertainty is precisely why home country bias can be a problem. If a large proportion of your portfolio is concentrated in the UK, the success of your investment and retirement plans becomes more dependent on the performance of one market, its dominant sectors and the economic factors affecting it.
A globally diversified portfolio spreads your investment exposure across a much wider range of countries, companies, sectors and economic environments. When one part of the global market performs poorly, other areas may behave differently, reducing your reliance on any single source of investment returns.
This does not mean that global diversification will always produce higher returns, nor does it eliminate investment risk. Global markets can fall together, and diversification cannot protect a portfolio from every loss. Its purpose is to reduce unnecessary concentration risk and avoid making your financial future dependent on correctly predicting which market will outperform next.
For British expats, this becomes particularly relevant because your existing UK pensions and investments may represent only one part of an increasingly international financial life. Where you live, where you expect to retire, the currencies in which you will eventually spend your money and the location of your other assets should all be considered as part of your wider investment and retirement planning.
Ultimately, overcoming home country bias is not about avoiding UK investments. It is about making sure your exposure to the UK is deliberate and appropriate rather than simply the result of familiarity, habit or investments accumulated over many years.
Frequently Asked Questions About Home Country Bias
What is home country bias?
Home country bias is the tendency to invest a disproportionately large amount of your portfolio in companies and assets from your own country. For British investors, this can mean holding significantly more UK investments than the UK’s relatively small share of global equity markets might suggest.
Why can home country bias increase investment risk?
Holding too much of your portfolio in one country can increase concentration risk. Your investments may become more dependent on the performance of a particular economy, stock market and group of sectors. Diversifying globally can spread this exposure across a wider range of countries, companies and industries, although diversification does not eliminate investment risk.
How can home country bias affect British expats?
British expats may retain UK pensions, investment funds, employer shares and other assets accumulated before moving abroad. They may then acquire additional investments in their new country of residence. Over time, this can create a portfolio shaped more by where they have previously lived and worked than by a deliberate investment strategy.
How do I know if my portfolio has too much UK exposure?
Start by looking through your pensions, investment accounts and funds to identify the underlying investments. You should consider your total UK exposure across your entire portfolio rather than looking at each account separately. Employer shares and other concentrated holdings should also be included when assessing your overall position.
Does having a UK pension mean my money is invested in the UK?
No. A UK pension does not automatically mean that the underlying investments are predominantly UK-based. Many UK pension funds invest across international markets. The geographical exposure of your pension depends on the funds and investments held within it, which is why it is important to examine the underlying holdings rather than simply where the pension itself is based.
Are UK multinational companies enough to provide global diversification?
Not necessarily. A UK-listed multinational may generate a substantial proportion of its revenue overseas, giving investors exposure to different economies and currencies. However, owning UK multinational companies is not the same as holding a portfolio diversified directly across companies, countries and markets worldwide.
What is the difference between geographical diversification and currency diversification?
Geographical exposure describes where your investments and their underlying businesses are exposed, while currency exposure relates to the currencies that can influence the value and returns of those investments. The two are connected but are not the same. This can be particularly important for British expats who may invest, earn income and eventually spend their retirement money in different currencies.
Does global diversification guarantee better investment returns?
No. Global diversification does not guarantee higher returns or prevent investment losses. Its purpose is to reduce unnecessary dependence on the performance of a single country, company or sector. Because nobody knows which markets will perform best in the future, diversification can help spread concentration risk across a broader investment portfolio.
How can I reduce home country bias?
The first step is to understand your existing exposure across all of your pensions and investments. If your portfolio is excessively concentrated in your home market, broader global investments may help diversify your exposure across different countries, companies and sectors. The appropriate allocation will depend on your objectives, attitude to risk, time horizon and wider financial circumstances.
Should British expats review their investments after moving abroad?
Moving abroad can be a useful point at which to review your overall investment strategy. Your country of residence, future retirement destination, expected spending currencies, existing pensions and investments, tax position and long-term financial objectives may all have changed. Investment and tax rules can also differ between countries, so specialist tax advice may be required where cross-border taxation is involved.

Talk to an Expert
Home country bias can create concentration risk without it being immediately obvious. UK pensions, investment funds, employer shares and other assets accumulated over many years can collectively leave you with much greater exposure to the UK than you intended. For British expats, the picture can become more complex when your investments, residence, future retirement plans and spending currencies span more than one country.
I’m Ross Naylor, a UK-qualified Chartered Financial Planner and Pension Transfer Specialist with nearly 30 years’ experience helping British expats and internationally mobile families with holistic financial planning, pensions, investments and retirement planning.
I firmly believe your location in the world should never be a barrier to expert, impartial and transparent financial advice you can trust.
If you are concerned that your portfolio may be too heavily concentrated in UK assets, I can help you understand your underlying investment exposure and consider how your pensions and investments fit into your wider financial plan. This includes looking at diversification, investment risk, currency considerations, where you expect to live in retirement and how your portfolio aligns with your longer-term objectives.
Book a Discovery Call