Retirement planning lessons for expats from Robert de Niro
TL;DR
Retirement planning is not just about how much wealth you have — it is also about having access to your money when you need it. Maintaining an appropriate emergency fund and sufficient liquidity can help you avoid selling investments during a market downturn or becoming trapped in unsuitable long-term products. For British expats, particular care should be taken with offshore bonds, structured products and other investments that may carry exit penalties or restrict access to capital. Before investing, understand not only the potential return, but also the costs, risks and how easily you can get your money back.
Planning for Retirement? Learn From Other People’s Experience
Retirement planning is about much more than building the biggest pension pot possible. The decisions you make about when to retire, how much income you need, how you invest and how you use your pensions and other assets can ultimately have just as much impact on your retirement as the amount you have saved.
Many costly retirement mistakes can be avoided with forward planning. Decisions made in the years immediately before and after retirement can have long-term consequences. Understanding your options before accessing pensions, changing investments or committing to a particular retirement income strategy gives you greater flexibility.
Every retirement journey is different. Your pensions, investments and savings are important, but so are your lifestyle, family circumstances, retirement age, future spending plans and where in the world you intend to live. A successful retirement plan needs to bring all of these factors together.
Your retirement plan also needs to be able to adapt. Investment markets change, inflation affects spending power, tax rules evolve and your priorities may look very different ten or twenty years into retirement. Building flexibility into your financial plan can help you respond without losing sight of your long-term objectives.
A Discovery Call can help you understand whether your current plans support the retirement you want. By reviewing your pensions, investments, expected retirement income and wider financial position together, you can identify potential gaps, explore your options and make informed decisions with greater confidence.
If you’re approaching retirement or simply want to know whether your existing plans are on track, book a Discovery Call to discuss your circumstances and the retirement you want to achieve.
The Robert de Niro Experience
According to an article in the magazine Page 6, even Robert de Niro’s finances have been affected by the COVID19 pandemic.
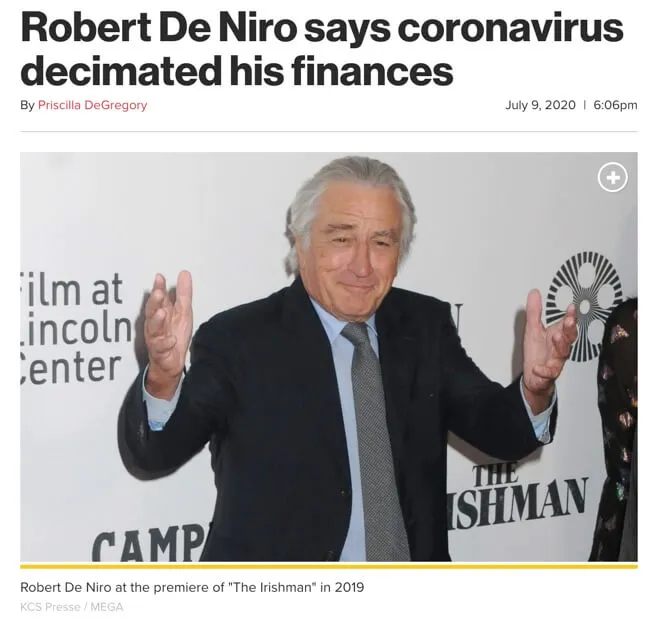
The issue is his stake in the restaurant and hotel chain Nobu.
Obviously, their venues have been closed or partially closed for months with barely any business coming in.
This has dealt a big blow to his finances.
According to his lawyer, Caroline Krauss, Nobu lost $3 million in April and another $1.87 million in May.
He was also due to pay $500,000 to investors, which he needed to borrow from his business partners, “because he [didn’t] have the cash,”
As a result, he has had to cut the monthly limit on his estranged wife’s Amex card from $100,000 to $50,000. How will she cope?
However, you needn’t worry about seeing him selling the Big Issue any time soon. He is still said to be worth $500 million and expects to earn $7.5 million this year.
In reality, this is a liquidity issue and is something that we can all take some lessons from.
Retirement lessons from the Godfather
Have an emergency fund
Businesses fail. Jobs don’t work out the way you hoped. Investments can go awry. Life tends to get in the way of even the best-laid financial plans.
I normally recommend that clients who are still working keep at least six months worth of expenses on deposit in the bank.
I know this means that your return on this money will be negligible. As I am writing this, Barclays have just cut the rate on their deposit account to 0.01 per cent.
However, by doing so, you can at least be certain that the money will be there when you really need it and you won’t run the risk of having less than you originally invested.
If you have retired already, or are very close to it, and are living from investment income, I would recommend having a greater amount available in cash.
That way, if markets do suffer a severe correction, you can live from your cash, while you wait for your investments to recover their value.
Liquidity is essential
Robert de Niro is struggling financially despite being worth $500 million because all of his money is tied up in illiquid investments.
Investment illiquidity can also affect those in retirement. This is largely due to investors being stuck in structures such as offshore bonds or funds that they are unable to get out of, at least without incurring high costs.
The key with any investment is knowing the terms and conditions for getting out of it before getting into it.
Offshore Bonds
I have seen expats unable to access their Pension Commencement Lump Sum when they want to because they have transferred their pension to a QROPS that includes an offshore bond.
These bonds are typically provided by companies like of Old Mutual/Quilter International, Utmost/Generali or Friends Provident.
The problem lies in the fact that there are often penalties to access money from these bonds. The fees often apply during the first 5-10 years of them being set up.
It is poor advice for anyone to be locked into such a structure when they are close to retirement.
Real People, Real Results
“I have consistently gone back to Ross to seek advice as my situation has changed and I have also talked about and recommended Ross to several expat colleagues.
Ross is a great sounding board and very comfortable providing advice to those already with some knowledge of investing and those who are just starting out.”
— David Harrington
More TestimonialsOffshore bonds are popular with expats, but are they really suitable?
In theory, offshore investment bonds can be an excellent investment vehicle for British expats.
The reason for this is that they have certain features that make them effective tax planning tools, especially for higher net worth individuals.
These benefits can accrue to those both living and working outside the UK permanently and to those who, at some point in the future, will return.
Caution is needed when it comes to setting up an offshore bond however.
Many international financial advisers will set these bonds up on a commission basis.
The issue with this is that the bond company (Old Mutual/Quilter International, Utmost/Generali, Friends Provident, RL360) will pay a commission to the adviser, up-front on day one, and then nothing thereafter.
As a result, there is no real incentive for the adviser to look after you properly once the bond has been set up and the adviser remunerated.
Fee only
With that in mind, I believe that offshore bonds should only ever be set up on a fee only basis.
This means that your interests and those of your adviser are aligned.
The adviser charges a fee, for ongoing advice, rather than collecting a large upfront commission from when the bond is first set up and as the client you only pay a fee for as long as you continue to be happy with what your adviser is doing for you.
Is Your Retirement Plan Still on Track?
A retirement plan should never be something you create once and then forget about. Your finances, lifestyle and priorities can change considerably over time, which means the strategy that looked right several years ago may no longer be the best fit for the retirement you now want.
Your retirement plans should evolve as your life changes. You may decide to retire earlier or later, move abroad, spend more during the first years of retirement, help children or grandchildren financially, or leave a larger inheritance. Each of these decisions can affect how your pensions, investments and other assets should be managed.
Investment markets, inflation and tax rules also change. A period of weaker investment returns or higher-than-expected inflation can affect the sustainability of retirement income, while changes to pension and tax rules may create new considerations. Regularly reviewing your strategy helps you respond to these developments rather than relying on assumptions made years earlier.
A regular review can help identify potential gaps before they become problems. Looking at your expected spending, pension income, investment portfolio, cash reserves and other assets together can provide a clearer picture of whether your financial resources remain aligned with your long-term retirement goals.
Independent financial advice can also help you explore opportunities you may have overlooked. This could include reviewing how you draw retirement income, how your investments are structured or how your wider financial plan supports both your lifestyle and the legacy you would eventually like to leave.
If you’re approaching retirement or haven’t reviewed your retirement strategy recently, book a Discovery Call to discuss your circumstances and whether your current financial plan remains aligned with the retirement you want.
Structured Products
Structured products are often advertised as the ideal vehicle to help you benefit from excellent stock market performance while simultaneously protecting you from bad market performance.
What’s not to like in that?
Well, structured products are complex instruments where the true risks are often not understood by financial advisers, never mind the client.
One of the biggest risks is liquidity, or the lack thereof.
Structured notes rarely trade on the secondary market after they have been issued, which means they can be punishingly illiquid.
If you do need to get your money out for whatever personal reason—or because the market is crashing—your only option for an early exit is to sell to the original issuer and that original issuer will know that you are in a fix.
As a result, it is unlikely that they will give you a good price—assuming they are willing or able to making you an offer at all.
Suspended funds
Finally, there are funds that have been suspended.
The international financial services market place is littered with tragic cases where funds have been suspended.
This happens due to factors ranging from poor investment decisions through to outright fraud.
Off the top of my head, names such as Mansion Student Accommodation, EEA, Axiom Legal Financing, DeVere Strategic Growth, Quadris Environmental Forestry, Premier New Earth and LM come to mind.
Once a fund has been suspended, investors can wait for years before their money is returned. In the majority of cases, even when they do get money back it is a small fraction of the pre-suspension value.
Having a lot of money doesn’t necessarily make you better at managing it
Johnny Depp has made three-quarters of a billion-dollars on his films. However, he basically lives paycheck to paycheck because of his spending habits.
He once admitted, “I’m not a lawyer. I’m not an accountant. I’m not qualified to help my 15-year-old son with his math homework…I’ve always trusted the people around me.”
Wealthy people are just as likely as anyone else to mess up their finances. It doesn’t matter how much money you make if you have more going out than you have coming in.
For sure, earning more will make it easier to become wealthy in theory. However, it doesn’t guarantee financial success. If you can’t prioritize your spending habits, you’ll never be able to save enough to retire on your terms, no matter how much money you earn.
Good Retirement Planning Brings Every Part of Your Finances Together
A successful retirement plan is about much more than deciding when to stop working or building the largest pension pot possible. Your pensions, investments, savings, tax position, expected spending and long-term goals all need to work together. Bringing these different elements into a single financial plan can give you a much clearer picture of what your retirement could look like and whether your resources are likely to support the lifestyle you want.
Define What Retirement Actually Means to You
Before deciding how much money you need, it helps to understand what you want retirement to look like. Some people want to stop working completely, while others prefer a gradual transition. You may want to travel extensively, spend more time with family, move abroad or simply enjoy greater freedom over how you spend your time. Defining those goals gives your financial plan something meaningful to work towards.
Build a Sustainable Retirement Income
Retirement often means moving from accumulating wealth to using it to support your lifestyle. That requires careful consideration of how much income you need, where that income will come from and how long your assets may need to last. State pensions, workplace pensions, personal pensions, investments, savings and other assets can potentially contribute to your retirement income, but they need to be considered together rather than in isolation.
Manage Your Pensions and Investments Together
Your pension is only one part of your retirement finances. ISAs, investment portfolios, cash savings and other assets may also play an important role. Looking at your pensions and investments as part of the same strategy can help you decide which assets to use for income, which to leave invested and how much investment risk is appropriate as you move through retirement.
Plan for Inflation and a Longer Retirement
Retirement could potentially last for several decades, making longevity an important part of financial planning. Inflation also means that the amount needed to maintain your lifestyle is unlikely to remain static. A retirement plan therefore needs to consider not simply whether you have enough money today, but whether your income and assets can continue supporting your spending needs over the long term.
Think Carefully About Tax-Efficient Withdrawals
The order in which you draw money from pensions, investments and savings can affect the amount of tax you pay during retirement. Rather than automatically taking income from one source, a coordinated withdrawal strategy can consider your available allowances, expected income and wider financial position. For British expats, this can become even more important because the tax treatment of UK pensions and investments may differ according to the country in which you are resident.
Consider Estate Planning and Passing on Wealth
Retirement planning is not necessarily only about providing income for yourself. You may also want to support children or grandchildren, make lifetime gifts or leave assets to particular beneficiaries. Considering estate planning alongside your retirement income requirements can help you balance enjoying your wealth during your lifetime with your longer-term wishes for your family.
Prepare for the Unexpected
Even the most carefully constructed retirement plan cannot predict everything. Investment markets can fall, spending requirements can change and unexpected family or financial circumstances can arise. Maintaining sufficient flexibility and appropriate cash reserves can help you respond to changing circumstances without having to abandon your wider retirement strategy.
Review Your Retirement Plan Regularly
Retirement planning does not end on the day you retire. Your spending, investments, family circumstances and priorities can change considerably over time, while tax and pension rules may also evolve. Regular reviews allow you to assess whether your retirement income remains sustainable and make adjustments when necessary rather than waiting until a problem develops.
The most successful retirement plans are not built around one pension or one investment. They bring retirement income, pensions, investments, tax planning, estate planning and lifestyle goals together into a flexible strategy that can adapt as your circumstances and priorities change throughout retirement.
Common Retirement Planning Mistakes People Make
Even a substantial pension or investment portfolio does not automatically guarantee a comfortable retirement. Successful retirement planning requires decisions about income, spending, investments, tax and long-term financial priorities to work together. Recognising some of the most common retirement planning mistakes can help you make better-informed decisions and build a plan that remains sustainable as your circumstances change.
Leaving Retirement Planning Too Late
It is easy to put retirement planning off while retirement still feels years away. However, the earlier you understand what your preferred retirement lifestyle might cost and compare that with your existing pensions, investments and savings, the more time you have to address any potential shortfall. Waiting until shortly before retirement can significantly reduce the options available to you.
Underestimating How Long Retirement Could Last
Retirement may need to be funded for several decades. Planning around an unrealistically short timeframe can increase the risk of drawing too much from your pensions and investments during the early years. A sustainable retirement strategy needs to consider longevity alongside your expected spending and available financial resources.
Focusing Only on the Size of Your Pension
The value of your pension is important, but it does not tell you whether your retirement plan will work. What matters is how your pensions interact with your State Pension, investments, savings, property and other sources of income. Looking at your overall financial position provides a much more useful picture of the retirement lifestyle you may be able to sustain.
Ignoring the Long-Term Impact of Inflation
Inflation gradually reduces the purchasing power of money. An income that comfortably covers your lifestyle when you first retire may buy considerably less many years later. Retirement planning therefore needs to consider how spending requirements could increase over time rather than assuming your income needs will remain unchanged.
Taking Too Much or Too Little Investment Risk
Moving everything into low-risk assets at retirement may appear reassuring, but your money may still need to remain invested for many years. Equally, taking excessive investment risk can expose money needed for retirement income to significant market fluctuations. The appropriate balance depends on your circumstances, income requirements, investment timeframe and capacity to absorb losses.
Forgetting About Tax in Retirement
The amount you withdraw from your pensions and investments is not necessarily the amount available to spend. Different sources of retirement income can have different tax consequences, and the order and timing of withdrawals can affect your overall position. For British expats, additional considerations may arise because UK pensions and investments can be treated differently in the country where you are tax resident.
Failing to Keep Beneficiary Nominations and Estate Plans Up to Date
Retirement is also an appropriate time to review what should happen to your wealth when you die. Pension beneficiary nominations, wills and wider estate planning arrangements can become outdated following marriage, divorce, bereavement or other family changes. Keeping these arrangements under review helps ensure they continue to reflect your wishes and current circumstances.
Not Keeping Enough Flexibility in Your Retirement Plan
It is impossible to predict exactly what retirement will look like twenty or thirty years in advance. Spending can change, family members may need financial support and unexpected costs can arise. Building flexibility into your plan and maintaining appropriate cash reserves can make it easier to respond without unnecessarily disrupting your longer-term strategy.
Failing to Review Your Retirement Plan Regularly
Retirement planning does not finish when you stop working. Investment performance, spending patterns, tax and pension rules, family circumstances and your own priorities can all change. Regular reviews provide an opportunity to check whether your retirement income remains sustainable and make adjustments when circumstances require them.
Successful retirement planning is an ongoing process rather than a one-off event. Reviewing your pensions, investments, retirement income, spending and tax position regularly can help ensure your financial plan continues to support the lifestyle you want while remaining flexible enough to adapt throughout retirement.

Talk to a Retirement Planning Expert
A successful retirement plan is about much more than accumulating the largest pension pot possible. It means understanding how your pensions, investments, retirement income, tax position and long-term lifestyle goals work together — and having a strategy flexible enough to adapt as your circumstances change.
I'm Ross Naylor, a UK-qualified Chartered Financial Planner and Pension Transfer Specialist with nearly 30 years' experience helping individuals and British expats make informed decisions about their pensions, investments and retirement. My approach is based on holistic financial planning, looking at your complete financial position rather than individual products in isolation.
Retirement can involve some of the most important financial decisions you'll ever make: when to retire, how much income to draw, how your money should remain invested and how to make your resources last throughout retirement. For British expats and internationally mobile families, those decisions can become more complex when different tax systems, currencies and residency rules are involved.
I firmly believe your location in the world should never be a barrier to expert, impartial and transparent financial advice you can trust. The objective is not simply to reach retirement with enough money, but to create a practical long-term financial plan that supports the life you want to live.
If you're approaching retirement, already retired or simply want to understand whether your current plans remain on track, a Discovery Call is an opportunity to discuss your circumstances, priorities and the retirement you want to achieve.
Book a Discovery Call